Slewing Scraper Market Size
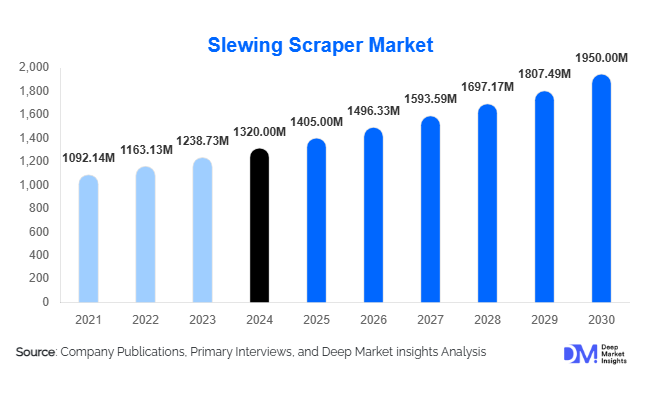
The global slewing scraper market was valued at USD 1,320 million in 2025 and is projected to reach approximately USD 2,326.92 million by 2034, expanding at a CAGR of 6.5% during 2026–2034. The market is estimated at USD 1,406 million in 2026, reflecting continued investment in mining, construction, infrastructure development, and industrial material-handling equipment.
Continued investment in mining and quarrying, infrastructure construction, bulk-material handling, and industrial facilities supports market growth. These activities require equipment capable of moving, reclaiming, loading, and handling large quantities of bulk material while maintaining operational efficiency.
Mining remains an important demand mechanism because material-handling operations increasingly require equipment that can operate continuously across large stockpiles, excavation areas, and processing facilities. The International Energy Agency reported that investment by large integrated mining companies continued to increase even as overall critical-mineral investment became more cautious in 2024.
The industry is also shifting toward equipment that combines higher material-handling productivity, automation, electrification, and lower operating expenses. This transition is particularly relevant for large industrial installations where equipment utilization and energy consumption have a direct effect on operating economics.
Key Takeaways
- Market growth: USD 1.32 billion in 2025, reaching approximately USD 2.33 billion by 2034 at 6.5% CAGR.
- Leading type: Hydraulic slewing scrapers hold an estimated 48.0% share.
- Fastest type: Electric slewing scrapers are estimated to grow at 7.5% CAGR.
- Leading application: Mining accounts for approximately 46.0% share.
- Regional leader: Asia Pacific holds approximately 42.0% share, while Middle East & Africa is the fastest-growing region at 7.3% CAGR.
Slewing Scraper Market Trends
The Market Is Shifting Toward Electrified Material-Handling Systems
The market is moving toward electric equipment as industrial operators seek to reduce fuel consumption and improve operational efficiency. Broader growth in electricity investment and industrial electrification is driving this trend.
This shift is increasing the importance of motor efficiency, electrical integration, remote monitoring and equipment lifecycle economics when companies evaluate new material-handling systems.
Equipment Design Is Moving Toward Greater Automation
The market is increasingly incorporating automation, sensors and remote monitoring into material-handling operations. These capabilities allow operators to monitor equipment performance, identify maintenance requirements and optimize material movement.
The competitive importance of equipment intelligence is therefore increasing alongside mechanical capacity and reliability.
Slewing Scraper Market Drivers
Expansion of Mining Projects Increases Demand for Bulk-Material Handling Equipment
Mining and quarrying operations require continuous movement of extracted material between excavation, processing, stockpiling and transportation stages. Expansion and modernization of these operations therefore creates demand for specialized material-handling equipment.
The IEA reports that large integrated mining companies continued to raise investment in 2024, despite weaker overall critical-mineral investment, while copper-focused companies increased spending as expectations for long-term demand remained positive.
This investment creates additional requirements for equipment capable of handling bulk materials efficiently. Slewing scraper systems can support material movement and reclaiming operations where controlled handling and equipment reach are important. Port Throughput Growth Supports Material-Handling Equipment Demand
Higher cargo volumes increase the requirement for efficient bulk-material movement at ports, terminals and logistics facilities. UN Trade and Development reported that global container port throughput reached 920 million TEUs in 2024, a 6.9% year-on-year increase.
Although containerized cargo is not the same as bulk-material handling, the continued growth of port activity increases the need for investment in terminal infrastructure and material-flow systems. This supports opportunities for equipment suppliers serving ports, harbors and industrial logistics facilities.
Industrial Electrification Is Increasing Interest in Electric Material-Handling Equipment
As equipment fleets modernize, industrial operators are placing greater emphasis on energy efficiency and electrification. Global energy investment is projected to reach USD 3.3 trillion in 2025, with electricity-related investment reaching approximately USD 1.5 trillion.
For equipment manufacturers, this transition creates opportunities to develop electric slewing scraper configurations that reduce reliance on diesel fuel and work better with automated industrial facilities.
Slewing Scraper Market Restraints
High Equipment and Installation Costs Limit Adoption
Slewing scraper systems can require substantial investment in equipment, installation, foundations, electrical or hydraulic systems, and supporting material-handling infrastructure.
This creates a higher initial investment requirement compared with simpler material-handling equipment. Cost-sensitive mining, construction and industrial operators may therefore delay replacement or select conventional alternatives where automation and high utilization do not justify the additional investment.
Mining Investment Volatility Creates Procurement Uncertainty
Mining equipment demand closely tracks commodity prices and mining-company capital expenditure. The IEA reported that global critical-mineral investment declined 9% in 2025, while battery-metal investment fell by more than 20%.
Lower commodity prices can cause mining companies to postpone expansion projects, directly affecting orders for new material-handling systems.
Slewing Scraper Market Opportunity
Automation Creates Opportunities for Advanced Slewing Scraper Systems
Industrial operators are increasingly looking for equipment that can operate with greater automation, monitoring and process integration. Automated slewing scraper systems can potentially reduce manual intervention while improving material-flow consistency.
Equipment manufacturers capable of integrating sensors, remote monitoring, automated positioning and condition monitoring can therefore differentiate their systems from conventional mechanical alternatives.
Mining Electrification Creates Opportunities for Electric Scrapers
The move toward more electrification is good news for companies that make electric slewing scrapers. Electrified systems can align with mining companies' efforts to reduce diesel consumption and improve energy efficiency.
This opportunity is particularly relevant to large fixed installations where electrical infrastructure is already available and equipment operates for extended periods.
Report Scope
| Report Metric | Details |
|---|---|
| Market Size in 2025 | USD 1320 Million |
| Market Size in 2026 | USD 1406 Million |
| Market Size in 2034 | USD 2326.92 Million |
| CAGR | 6.5% (2026-2034) |
| Base Year for Estimation | 2025 |
| Historical Data | 2022-2024 |
| Forecast Period | 2026-2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Supply Chain Disruption, Growth Factors, Environment & Regulatory Landscape and Trends |
| Geographies Covered | North America, Europe, APAC, Middle East and Africa, LATAM |
| Countries Covered | U.S., Canada, U.K., Germany, France, Spain, Italy, Russia, Nordic, Benelux, Rest of Europe, China, Korea, Japan, India, Australia, Singapore, Taiwan, South East Asia, Rest of Asia-Pacific, UAE, Turky, Saudi Arabia, South Africa, Egypt, Nigeria, Rest of MEA, Brazil, Mexico, Argentina, Chile, Colombia, Rest of LATAM |
Explore more data points, trends and opportunities Download Free Sample Report
Slewing Scraper Market Segmentation Analysis
By Type
The hydraulic slewing scraper segment held the largest market share, at around 48.0% in 2025, generating approximately USD 633.6 million. The segment is estimated to grow at a 6.3% CAGR, reaching approximately USD 1,102 million by 2034.
Its leading position is supported by the established use of hydraulic systems for controlled movement and positioning in heavy-duty equipment. Hydraulic actuation provides high force density and is suitable for demanding industrial and mining environments where equipment must repeatedly position and handle heavy loads.
Continued investment in mining, construction and bulk-material handling infrastructure is expected to maintain demand for hydraulic configurations.
Electric slewing scrapers are estimated to record the fastest growth at approximately 7.5% CAGR through 2034.
Industrial electrification and the need to reduce diesel dependence in fixed or semi-fixed material-handling applications support this growth. The broader energy-investment transition toward electricity strengthens the commercial case for electrified equipment.
As industrial operators prioritize energy efficiency and emissions reduction, electric configurations are expected to gain share, particularly in facilities with established electrical infrastructure.
Diesel-powered systems remain relevant where equipment operates in remote mining, construction or infrastructure environments without reliable access to electrical infrastructure. Their mobility and established fuel supply networks support continued use, although electrification is expected to limit their long-term growth relative to electric alternatives.
By Capacity
Small-capacity systems serve lower-volume material-handling operations and applications where equipment footprint and maneuverability are more important than maximum throughput.
The medium-capacity systems segment held the largest market share, at around 43.0% in 2025, equivalent to approximately USD 567.6 million. The segment is estimated to grow at approximately 6.5% CAGR, reaching around USD 1,002 million by 2034.
Its position is supported by its suitability across construction, industrial plants, quarrying and medium-scale material-handling operations.
Large-capacity slewing scrapers are estimated to grow at approximately 7.3% CAGR, making them the fastest-growing capacity category.
Growth is supported by large-scale mining and industrial operations where higher material throughput can improve productivity and reduce the number of equipment cycles required to move bulk materials.
By Application
The mining segment held the largest market share, at around 46.0% in 2025, generating approximately USD 607.2 million. The segment is estimated to grow at 6.7% CAGR, reaching approximately USD 1,086 million by 2034.
Mining's leading position is supported by the large volumes of material that must be moved between extraction, processing and stockpiling areas. Continued investment in mineral supply chains provides an underlying demand base for heavy material-handling systems.
Construction applications include earthmoving, bulk-material movement and infrastructure development. Demand is supported by ongoing investment in roads, industrial facilities and other large construction projects.
Civil infrastructure applications benefit from large-scale projects involving earth, aggregate and other bulk materials. Equipment capable of moving material efficiently can support productivity where material handling represents a significant part of project operations.
Ports & Harbors are estimated to record the fastest application growth at approximately 7.4% CAGR.
The continued expansion of global maritime trade and port infrastructure supports the growth outlook. UNCTAD reported that global container port throughput increased 6.9% in 2024 to 920 million TEUs.
As ports expand and modernize their material-flow infrastructure, they will drive increased demand for higher-productivity handling equipment.
Industrial material handling covers factories, processing facilities and large plants where bulk materials must be moved between storage and processing stages. Automation and the modernization of industrial handling systems support demand.
By End-Use Industry
The mining & quarrying segment held the largest market share, at around 45.0% in 2025, equivalent to approximately USD 594.0 million. The segment is estimated to grow at 6.7% CAGR, reaching approximately USD 1,064 million by 2034.
Its leadership reflects the high material volumes and demanding operating conditions associated with mineral extraction and aggregate production.
Construction and infrastructure represent a broad demand base because projects require the movement of aggregates, soil and other bulk materials. Continued infrastructure development supports equipment replacement and new-project demand.
Oil and gas facilities use material-handling systems across processing, storage and infrastructure operations. However, investment conditions remain mixed. The IEA expects global upstream oil investment to decline 6% in 2025 to approximately USD 420 billion, limiting near-term equipment investment in some oil-producing regions.
Manufacturing & industrial plants are estimated to record the fastest growth at approximately 7.2% CAGR.
Growth is supported by industrial modernization, automation and electrification. Operators increasingly require material-handling equipment that can integrate with automated production and storage systems while improving energy efficiency.
Explore more data points, trends and opportunities Download Free Sample Report
Slewing Scraper Market Segmentations
By Type
- Hydraulic Slewing Scraper
- Electric Slewing Scraper
- Diesel-Powered Slewing Scraper
By Capacity
- Small (up to 10 tons)
- Medium (10–25 tons)
- Large (25+ tons)
By Application
- Mining
- Construction
- Civil Infrastructure
- Ports & Harbors
- Industrial Material Handling
By End-Use Industry
- Mining & Quarrying
- Construction & Infrastructure
- Oil & Gas
- Manufacturing & Industrial Plants
Slewing Scraper Market Regional Analysis
Asia Pacific Slewing Scraper Market Insights
Asia Pacific Slewing Scraper industry dominated the global market, accounting for approximately 42.0% of revenue in 2025. The region's leading position is supported by its concentration of mining, manufacturing, construction, infrastructure and port activity.
Asia's importance in global material movement is particularly evident in maritime infrastructure. Developing economies in Asia handled approximately 60% of global container port traffic in 2024, according to UNCTAD. Global container port throughput reached 920 million TEUs that year.
The region also remains central to global industrial and energy investment. China is the world's largest energy investor, while its share of global clean-energy investment has risen to almost one-third over the past decade.
These industrial, mining and infrastructure activities create a broad customer base for heavy material-handling equipment. Asia Pacific is projected to grow at approximately 6.7% CAGR, reaching approximately USD 1,001 million by 2034 and maintaining its leading regional position.
Middle East & Africa Slewing Scraper Market Insights
Middle East & Africa is expected to be the fastest-growing region, expanding at approximately 7.3% CAGR.
Growth is supported by mining development, industrial diversification, infrastructure construction and investment in energy-related facilities. The region is also becoming increasingly important for upstream energy investment: the IEA expects the Middle East to account for approximately 20% of global upstream oil investment in 2025, its highest share on record.
Mining and infrastructure projects create demand for large-capacity material-handling systems, particularly where operations require continuous movement of bulk materials.
The regional market is estimated to increase from approximately USD 264 million in 2025 to USD 503 million by 2034.
North America Slewing Scraper Market Insights
North America is estimated to account for approximately 24.0% of the market in 2025, generating around USD 316.8 million.
The region benefits from established mining operations, industrial facilities, ports and infrastructure networks. Equipment replacement and modernization provide an important demand mechanism as operators seek higher productivity and greater automation.
The North American market is projected to grow at approximately 6.2% CAGR, reaching approximately USD 545 million by 2034.
Europe Slewing Scraper Market Insights
Europe is estimated to represent approximately 18.0% of the global market in 2025, equivalent to approximately USD 237.6 million.
The region's demand is supported primarily by industrial modernization, infrastructure development and efforts to improve energy efficiency. Electrification is particularly relevant as European industrial operators seek to reduce fossil-fuel consumption.
Europe is projected to expand at approximately 5.8% CAGR, reaching approximately USD 398 million by 2034.
Latin America Slewing Scraper Market Insights
Latin America is estimated to account for approximately 10.0% of the market in 2025, generating approximately USD 132.0 million.
Mining represents an important demand mechanism because the region contains major producers of copper, lithium, iron ore and other minerals. However, commodity-price volatility can influence capital expenditure and equipment procurement.
The regional market is estimated to grow at approximately 6.4% CAGR, reaching approximately USD 231 million by 2034.
Key Players in the Slewing Scraper Market
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment
- Liebherr Group
- Hitachi Construction Machinery
- Doosan Infracore
- Terex Corporation
- SANY Group
- XCMG Group
- JCB
- Kobelco Construction Machinery
- Wirtgen Group
- Zoomlion Heavy Industry
- Hyundai Construction Equipment
- Shantui Construction Machinery